Clarity across the credit lifecycle.
Independent guidance on consumer credit, lending regulation, BNPL, fair lending and credit compliance. Built for the teams making lending decisions.
The next consumer-credit chapter
CCD2: prepare for 20 November 2026
The national measures implementing Directive (EU) 2023/2225 apply from 20 November 2026. Start with scope, then map the rules to each market.
Read the entry ↗Find your starting point.
Credit compliance fundamentals
Map the product, parties and applicable framework before assessing a lending journey.
CCD2
Understand the revised EU framework, the application date and the importance of national implementing measures.
BNPL
Separate third-party credit from supplier deferred payment before assessing scope.
Creditworthiness & affordability
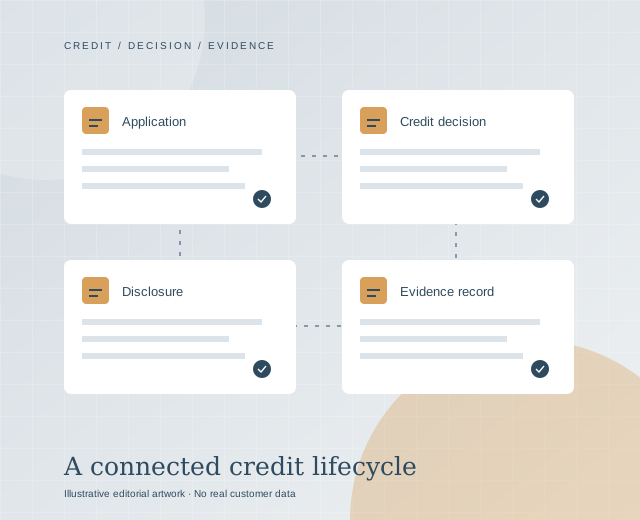
Connect application evidence, repayment capacity, decision records and review controls.
Credit advertising
Review claims, cost information and distribution channels as one controlled communication.
Pre-contract information & disclosures
Manage document versions, presentation, delivery and evidence of the customer journey.
Follow the decision.
Keep the evidence.
Requirements make more sense in context. Connect product scope to the borrower journey and the records behind each step.
Start with the framework ↗Useful questions. Clear pathways.
CCD2: application date and transition planning
20 November 2026 is the application date for the national measures required to transpose Directive (EU) 2023/2225. The deadline to adopt and publish those measures was 20 November 2025.
BNPL scope: the facts a review needs
A BNPL label does not determine CCD2 scope. Identify the credit provider, payment structure and conditions before drawing a conclusion about a particular arrangement.
How to research CCD2 national implementation
Country implementation research should distinguish the EU text, national legislation and regulator material. A useful record explains the source of each claim and what remains unresolved.
UK creditworthiness and affordability: review structure
FCA CONC 5.2A addresses both credit risk and affordability risk within a creditworthiness assessment. Keep the UK framework separate from CCD2 and examine the rules that apply to the agreement concerned.
Begin with the product facts.
Choose a jurisdiction and a research area to find the relevant entries and the authorities posted behind them.